
First, I wanted to share Tactile Fund LP’s third quarter letter. I am happy that Tactile is off to a great start in its inaugural year, but the true value the extraordinary physical assets in the Tactile portfolio will be proven in the years and decades ahead.
Letter: Tactile Fund LP Third Quarter 2025 Letter to Partners
Way back in 1810, a man named Ariovistus Pardee was born in the Hudson Valley. His father, also named Ariovistus, and mother, Emily, were farmers from descended from old English and Huguenot families. Ariovistus, often shortened to “Ario,” was educated at home and also received training in engineering from a Presbyterian minister. Young Ario went on to become a surveyor’s assistant during the construction of the Delaware and Raritan Canal, which enabled goods to be quickly and cheaply transported east-west across New Jersey. Among the most important of these goods was anthracite coal.
Commercial collieries had operated in Eastern Pennsylvania since 1792, but the difficulty and expense of transporting this coal from the rugged hills to the population centers of Philadelphia and New York hindered the industry’s growth. Canals were an early solution. But a revolutionary technology was just around the corner: rail! Railways would allow coal to be sent hundreds or thousands of miles away, quickly and at far lower cost. In 1840, while living in Hazleton, Pennsylvania and serving as superintendent of the Hazleton Railroad and Coal Company, Ario began buying nearby coal claims. Ario Pardee’s coalfields proved tremendously rich in anthracite. It wasn’t long before Ario was a very wealthy man.
Ario had a large family. Ario and his first wife, Elizabeth Jacobs, had birth to four children before Emily died in childbirth along with their fifth child. After her death, Ario hired a governess, Anna Robison, to assist in caring for the children. Ario soon married Anna and they had another nine children. During the Civil War, Ario funded a military unit that came to be called “Pardee’s Rifles.” Pardee’s son, Ariovistus Jr., fought in this unit and showed valor at Gettysburg, where a portion of the battlefield is named after him. After the war, Ariovistus took an interest in Lafayette College. His donations helped the college regain its financial footing. Pardee served as the institution’s president beginning in 1881.
Per his biographers, Ariovistus Pardee was well-known in his time and widely respected for his sound judgment, honesty, and charitable character. While he was not a warm or sociable man, he was evidently kind to his family and small circle of friends. Above all, Pardee believed in the principles of thrift and industry. He exhibited this industry well into his old age, expanding from coal into timber and iron smelting. Along the way, his companies amassed many thousands upon thousands of acres of timberlands and mineral rights across Appalachia.
Ario Pardee died in Florida at the age of 81. At the time of his death, he was one of the richest men in America, with a fortune of nearly $1 billion in today’s dollars.
We could end our story there, having briefly illuminated the life of a notable but now little-remembered American industrialist. If Pardee had been born a little later and set his sights on the bituminous coal across the Alleghenies, he might be mentioned in the same breath as Carnegie, Mellon, and Frick.
Pardee Resources Company
While many of 19th-century industrial fortunes evaporated in a matter of decades thanks to speculation and free-spending heirs, the Pardee fortune endures. Ario’s legacy lives on as Pardee Resources Company. Headquartered near Philadelphia and traded over-the-counter, Pardee remains a large landowner and earns millions annually from timber sales and mineral royalties.
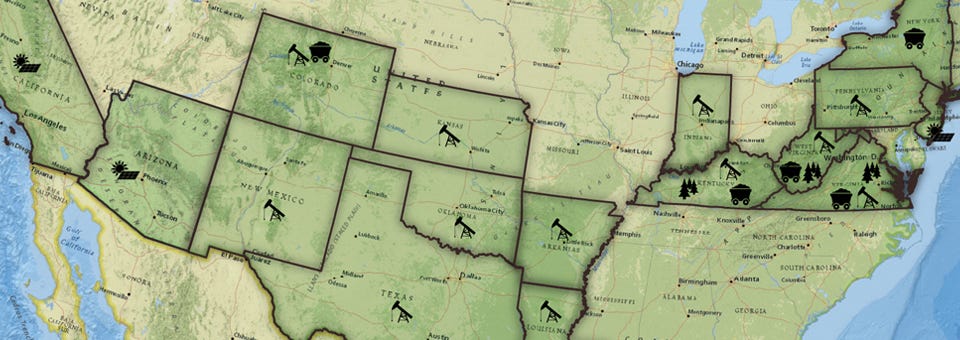
Pardee’s holdings span 15 states and include the following:
154,572 acres of timberland with 640 million board feet of hardwood reserves and 302 million board feet of softwood reserves. These timberlands are located in West Virginia, Virginia, and Kentucky.
140 million tons of metallurgical coal reserves and 176 million tons of thermal coal reserves in the Central Appalachian Basin. While thermal coal was once a big revenue source for Pardee, nearly all the company’s coal royalties are now derived from metallurgical coal.
23 billion cubic feet equivalents in natural gas reserves in Appalachia, Louisiana, and Colorado. The company’s Appalachian lands host 3,300 conventional natural gas wells with low decline rates, while the Colorado holdings produce more oil using unconventional wells.
Agricultural assets and solar power generation.
Because Pardee’s earnings are all commodity-related, single year results don’t tell us much about the company’s normal earnings power or its value. Far better to look at results over long periods of time. With that, here’s a look at Pardee’s operating earnings from its timber, coal, and oil & gas segments going back several years.
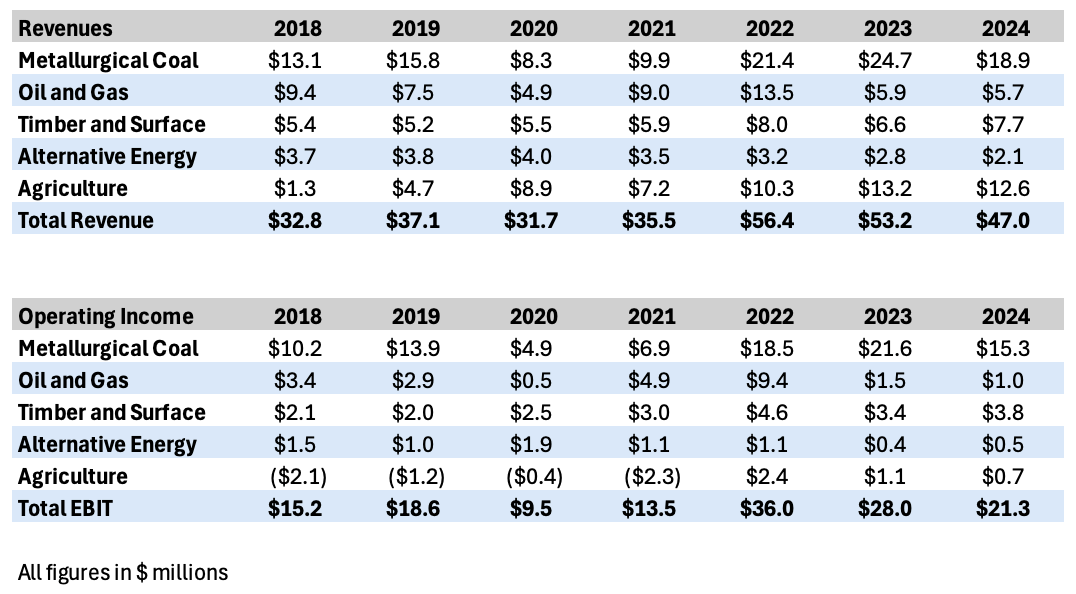
A few things jump out. First, Pardee is consistently profitable. Whether commodity prices are high or low, Pardee makes money. The joys of a royalty-like business model! Second, coal is Pardee’s most profitable and important asset, accounting for over 60% of operating income in most years. Oil & gas is the second-biggest contributor, though its results vary widely thanks to the volatility of natural gas. Timber is next and fairly consistent. Alternative energy is nearly an after-thought, and agriculture was a money-loser until recently.
Excluding agriculture and alternative energy, Pardee’s natural resource assets contributed operating income averaging $20.5 million from 2018 through 2024. In current dollars, that’s $22.3 million. Tack on another $1.5 million or so in normalized EBIT from alternative energy and agriculture and we’re at $23.8 million in average EBIT from operations.
I wish I could call it a day at this point, compare normalized EBIT with Pardee’s enterprise value, say “Hmmmm, looks kinda cheap!” and move on. But unfortunately, I have to address corporate overhead and strategy, and I have a few bones to pick.
Overhead and Strategy
Pardee’s corporate overhead runs about $6 million annually. That might not seem awful, but I think it is excessive by something on the order of 50% or so. Remember that Pardee doesn’t actually have to do all that much. It doesn’t conduct gas drilling or exploration, doesn’t perform its own timbering or acquire significant additional acreage, doesn’t install solar arrays, and doesn’t do its own farming. All Pardee really needs to do is negotiate lease agreements, collect checks, and send someone to check on its acreage now and then. It really seems like something that would take 10 employees at most. But Pardee has 10 employees in upper management alone, overseen by a seven member board.
Pardee also has a tendency to do something when doing nothing would be better. After all, those managers have to justify their paychecks. The company talks up its agricultural assets in every annual report, but I refuse to believe that Pardee has any competitive advantage in farming table grapes in California or almonds in Portugal. The company really does both and so far, the results have been dismal. Cumulative profit remains negative after 7+ years. The company’s alternative energy efforts have more successful, but far from impressive. A decade ago, Pardee got into a mess when a $7.7 million dollar investment in a mobile solar generation leasing arrangement turned out to be a Ponzi scheme. In fairness to Pardee, Berkshire Hathaway got tricked, too. But it wouldn’t have happened if Pardee had stuck to its core businesses of leasing its resources to drillers, miners, and loggers. Pardee is sticking with solar, recently spending $15.5 million to install solar panels on public school rooftops in Roanoke, Virginia. While I don’t have any particular reason to believe this is a bad investment, I do consider it an inferior use of capital compared to repurchasing shares or distributing dividends.
On the Subject of Trees
Timber is a strange (non-)animal. Small acreage tends to trade on the value that an owner/operator can derive from forestry operations, while big acreage, think tens of thousands of acres or more, becomes an “alternative investment asset” and is valued as such by pensions, endowments, and other large, long-term oriented pools of capital. In other words, a logging company will evaluate the lease or purchase of a timber tract by asking “At this price, can we achieve a short payback period and an attractive IRR?” while the Yale Endowment might think “At this price, can this timberland produce a mid single-digit real return?” It should be obvious which potential buyer has a lower cost of capital and is typically willing to pay quite a lot more.
So the question becomes, is Pardee’s timber worth what logging companies would pay for it, or what a pension fund would? Or maybe somewhere in the middle? Pardee doesn’t disclose what they think their timberlands are worth, but I did stumble across a 2014 appraisal that valued Pardee’s holdings at between and $937 and $1,064 per acre. Assuming their value has appreciated at 1% annually since and that the composition of the biological inventory is unchanged, that would make Pardee’s timber worth between $162 million and $183 million today, or between $249 and $281 per share, pre-tax.
Lest anyone get too excited, I should point out that Pardee recently sought offers for a 47,000 acre tract of timberland in West Virginia, but ultimately chose not to sell, deeming the offers insufficient. Still, I think it is reasonable to conclude that Pardee’s timberlands are worth the majority of Pardee’s current enterprise value and far in excess of their contribution to annual earnings.
Valuation
At $295 and with 651k shares outstanding, Pardee has a market capitalization of $192 million. The company has $37 million in cash and effectively zero debt for an enterprise value of $155 million. Crediting the company for its Roanoke solar installation and assuming agriculture produces some minimal operating profit going forward, Pardee appears to be trading at somewhere around 8.7x mid-cycle operating income, inclusive of drag from corporate overhead.
I think that’s reasonable for a company with stable earnings, an ironclad balance sheet, and a low-risk business model. Investors in Pardee at these prices get a good yield on normalized earnings, with plenty of upside potential from higher coal and natural gas prices. And natural gas prices are rising, up more than 100% from 2024 lows. I don’t think a major timberland sale is imminent, but a man can dream.
Despite my grumbling about excessive overhead and staffing and the company’s misadventures in farming and solar power, Pardee core assets are top-tier and I do think the company is reasonably well-managed. Shareholders have fared very well over the years. The last decade wasn’t one of Pardee’s better stretches, thanks to the rapid decline of thermal coal production. But Pardee’s valuation has declined to the point where I think the company’s forward return stream is likely to be attractive, particularly if commodities prices head higher. Happy researching!
Alluvial Capital Management, LLC holds shares of Pardee Resources Company for Tactile Fund LP and other client accounts it manages. Alluvial Capital Management, LLC may hold any securities mentioned on this blog and may buy or sell these securities at any time. For a full accounting of Alluvial’s and Alluvial personnel’s holdings in any securities mentioned, contact Alluvial Capital Management, LLC at info@alluvialcapital.com
The funniest part of each quarterly report is the Agricultural section:
'The results were expected to be good this year, with an expected production of XXX except for.YYY'
For YYY insert: weather was too hot, too cold, too wet, too dry, too wet and then too dry, no weather problems so harvest was so good for everyone that sales prices were very low, Polar Vortex, La nina, El nino, fungus, nut rot, mildew, insects, floods, immigration laws limiting harvesting, Sun spots, lunar cycles, earthquake in Nigeria, the plague, dogs and cats living together.
I have learned that farming is a tricky business from reading the Pardee reports year after year.
Thanks for the great writeup as always, Dave.
This is not about Pardee but about your “Alpine” investments in the fund - I fully agree that they are irreplaceable assets (I live in Switzerland). But how do you underwrite “disaster” risks? Floods, landslides etc can cause disruptions and even massive damage sometimes (like in Blatten this year).
This creates a dilemma where the assets are high quality and safe, but might require substantial capex every now and then. How do you incorporate this aspect into your assessment?